
Written by the Real Homes Realty Property Team | Last updated: May 2026
First home buyer Western Sydney opportunities in 2026 are more financially accessible than at any point in the past decade. Between government grants, stamp duty exemptions, 5% deposit schemes, and shared equity programs, eligible buyers can access tens of thousands of dollars in support before applying for a mortgage.
The challenge is not the availability of support — it is knowing which schemes you qualify for, which Western Sydney suburbs offer properties within the eligibility thresholds, and how to navigate a purchase process that most first home buyers have never done before.
Understanding the first home buyer Western Sydney market is essential before choosing a suburb, applying for grants, or speaking with lenders.
This guide covers everything: every government scheme available to NSW first home buyers in 2026, the best suburbs in Western Sydney for first home buyers, a step-by-step buying process, and the most common mistakes to avoid.
- What Government Support Is Available for First Home Buyers in NSW in 2026?
- Can You Stack Multiple Schemes?
- Best Suburbs for First Home Buyers in Western Sydney in 2026
- The Step-by-Step First Home Buyer Process in Western Sydney
- The Costs First Home Buyers in Western Sydney Often Miss
- Renting vs Buying in Western Sydney: Making the Right Decision for 2026
- Western Sydney First Home Buyer: Common Mistakes to Avoid
- How Real Homes Realty Helps First Home Buyers in Western Sydney
What Government Support Is Available for First Home Buyers in NSW in 2026?
NSW offers some of the most generous first home buyer support in Australia. The following schemes are available in 2026 — and in many cases, you can stack multiple schemes simultaneously.
Scheme 1 — First Home Owner Grant (FHOG): $10,000 Cash
The NSW FHOG is a one-off payment of $10,000 for eligible first home buyers purchasing or building a new home. The home must be brand new or substantially renovated — the FHOG is not available for established homes in NSW.
Key eligibility requirements:
- Australian citizen or permanent resident
- At least 18 years old
- Never owned or co-owned residential property in Australia (including investment properties)
- Must live in the home as your principal place of residence for at least 12 continuous months
- Property value must be under $600,000 (or $750,000 for house and land packages)
Where this matters in Western Sydney: The $600,000 cap makes this grant most relevant for buyers considering units, townhouses, or house and land packages in outer Western Sydney suburbs like Mount Druitt, St Marys, Werrington, and parts of Penrith. Established houses in Kellyville, Parramatta, or Blacktown frequently exceed the threshold.
Scheme 2 — First Home Buyers Assistance Scheme (FHBAS): Up to $31,335 in Stamp Duty Savings
This is often the most valuable scheme for Western Sydney first home buyers. The FHBAS provides a full or partial exemption from transfer duty (stamp duty) and — unlike the FHOG — applies to both new and existing properties.
Stamp duty thresholds (2026):
| Property Value | Stamp Duty Payable |
|---|---|
| Up to $800,000 | $0 — full exemption |
| $800,001 to $1,000,000 | Concessional sliding scale |
| Over $1,000,000 | Full stamp duty applies |
What this means in real dollars: Stamp duty on an $800,000 home in NSW would normally be approximately $31,335. Under the FHBAS, an eligible first home buyer pays $0 — a saving that goes directly towards your deposit or reduces how much you need to borrow.
Key eligibility requirements:
- Same ownership and residency requirements as the FHOG
- Must intend to live in the property as your principal place of residence for at least 12 continuous months
- No income cap applies
Where this matters in Western Sydney: The $800,000 full exemption threshold is achievable across a significant portion of the Western Sydney market — including units in Blacktown, Penrith, and Parramatta, and houses in outer suburbs. This is the scheme most Western Sydney first home buyers should prioritise understanding.
Scheme 3 — First Home Guarantee: Buy With 5% Deposit, No LMI
The federal First Home Guarantee allows eligible first home buyers to purchase with a 5% deposit and no Lenders Mortgage Insurance. The government guarantees the remaining 15% of the standard 20% deposit requirement.
Key features:
- Places are now unlimited — no annual cap
- No income caps apply
- Available through participating lenders
- Property price caps apply for Sydney
What LMI costs you without this scheme: On an $800,000 purchase with a 5% deposit ($40,000), Lenders Mortgage Insurance would typically cost $20,000 to $25,000. The First Home Guarantee eliminates this cost entirely.
Practical implication for Western Sydney buyers: A first home buyer purchasing a $750,000 property with a 5% deposit ($37,500) can access the guarantee through a participating lender. The remaining 95% is a standard mortgage. You still need to demonstrate genuine savings and serviceability.
Scheme 4 — Help to Buy: Government Contributes Up to 30% (New in 2026)
The federal Help to Buy shared equity scheme is the newest addition to the first home buyer toolkit. The government contributes up to 30% of a new home’s purchase price (25% for existing homes). You need as little as a 2% deposit.
How it works: On a $700,000 new home, the government contributes up to $210,000. You borrow only $490,000 plus your deposit — significantly reducing your monthly mortgage repayment. The government holds a proportional ownership stake, which you buy back over time.
Key eligibility requirements:
- Australian citizen
- Annual income under $90,000 (singles) or $120,000 (couples)
- Must not currently own property in Australia
- Must live in the property
Where this matters in Western Sydney: Help to Buy is particularly relevant for single-income first home buyers in Western Sydney who have stable employment but cannot save a conventional deposit quickly enough to access property in suburbs like Blacktown, Penrith, or Parramatta within a reasonable timeframe.
Scheme 5 — First Home Super Saver Scheme (FHSS): Up to $50,000 from Super
The FHSS allows eligible first home buyers to make voluntary contributions to their superannuation fund and withdraw up to $50,000 to use as a home deposit. Voluntary contributions are taxed at a lower rate within super (15%) compared to standard income tax — creating a tax-efficient savings vehicle.
How it works: Each financial year, you can contribute up to $15,000 in voluntary super contributions designated for the FHSS, up to a $50,000 total. When you are ready to purchase, you apply to the ATO to release the funds.
Example saving for a Western Sydney buyer on $90,000: Instead of saving outside super and paying income tax at 34.5% (including Medicare), the same savings inside super attract 15% tax — a difference of approximately $3,000 per $15,000 contributed. Over three years, the FHSS can meaningfully accelerate deposit accumulation.
Can You Stack Multiple Schemes?
Yes — and understanding how to combine them is where the real financial benefit lies. An eligible NSW first home buyer purchasing a $600,000 new home could potentially access all of the following simultaneously:
- $10,000 FHOG cash grant
- Full stamp duty exemption (saving approximately $22,000)
- First Home Guarantee (buy with 5% deposit, save $15,000+ in LMI)
- FHSS contributions (additional $50,000 in tax-efficient savings)
Combined potential benefit: $40,000 to $75,000+ in direct financial support, depending on schemes accessed, property price, and individual circumstances.
The key is confirming your eligibility for each scheme early — before you sign a contract. Some schemes require pre-approval through specific channels.
The first home buyer Western Sydney market still offers affordable suburbs under major NSW government support thresholds.
Best Suburbs for First Home Buyers in Western Sydney in 2026
The challenge for Western Sydney first home buyers is finding properties within the FHBAS $800,000 threshold — a threshold that rules out most established houses in Kellyville, Parramatta, and North Penrith, but still leaves a significant portion of the market accessible.
Under $600,000 — New Home Grant Eligible
| Suburb | Property Type | Approx. Price Range |
|---|---|---|
| Mount Druitt | Houses and units | $500,000 – $600,000 |
| St Marys | Units and townhouses | $500,000 – $600,000 |
| Werrington | Units | $500,000 – $600,000 |
| Kingswood | Units | $500,000 – $620,000 |
$600,000 – $800,000 — Stamp Duty Exemption Eligible
| Suburb | Property Type | Approx. Price Range |
|---|---|---|
| Penrith | Units | $520,000 – $750,000 |
| Blacktown | Units and townhouses | $480,000 – $750,000 |
| Granville | Units | $450,000 – $700,000 |
| Merrylands | Units | $490,000 – $750,000 |
| Auburn | Units | $480,000 – $720,000 |
| Parramatta | Units (outer areas) | $600,000 – $800,000 |
$800,000 – $1,000,000 — Partial Stamp Duty Concession
| Suburb | Property Type | Approx. Price Range |
|---|---|---|
| Penrith | Townhouses and smaller houses | $800,000 – $950,000 |
| Blacktown | Houses | $800,000 – $1,000,000 |
| Schofields | Townhouses | $800,000 – $950,000 |
Every first home buyer Western Sydney purchaser should understand the buying process before making an offer on a property.
The Step-by-Step First Home Buyer Process in Western Sydney
Step 1 — Know Your Budget Before You Search
The most common mistake first home buyers make is searching for properties before knowing their genuine borrowing capacity. This leads to disappointment when the properties they have been viewing are outside their actual budget.
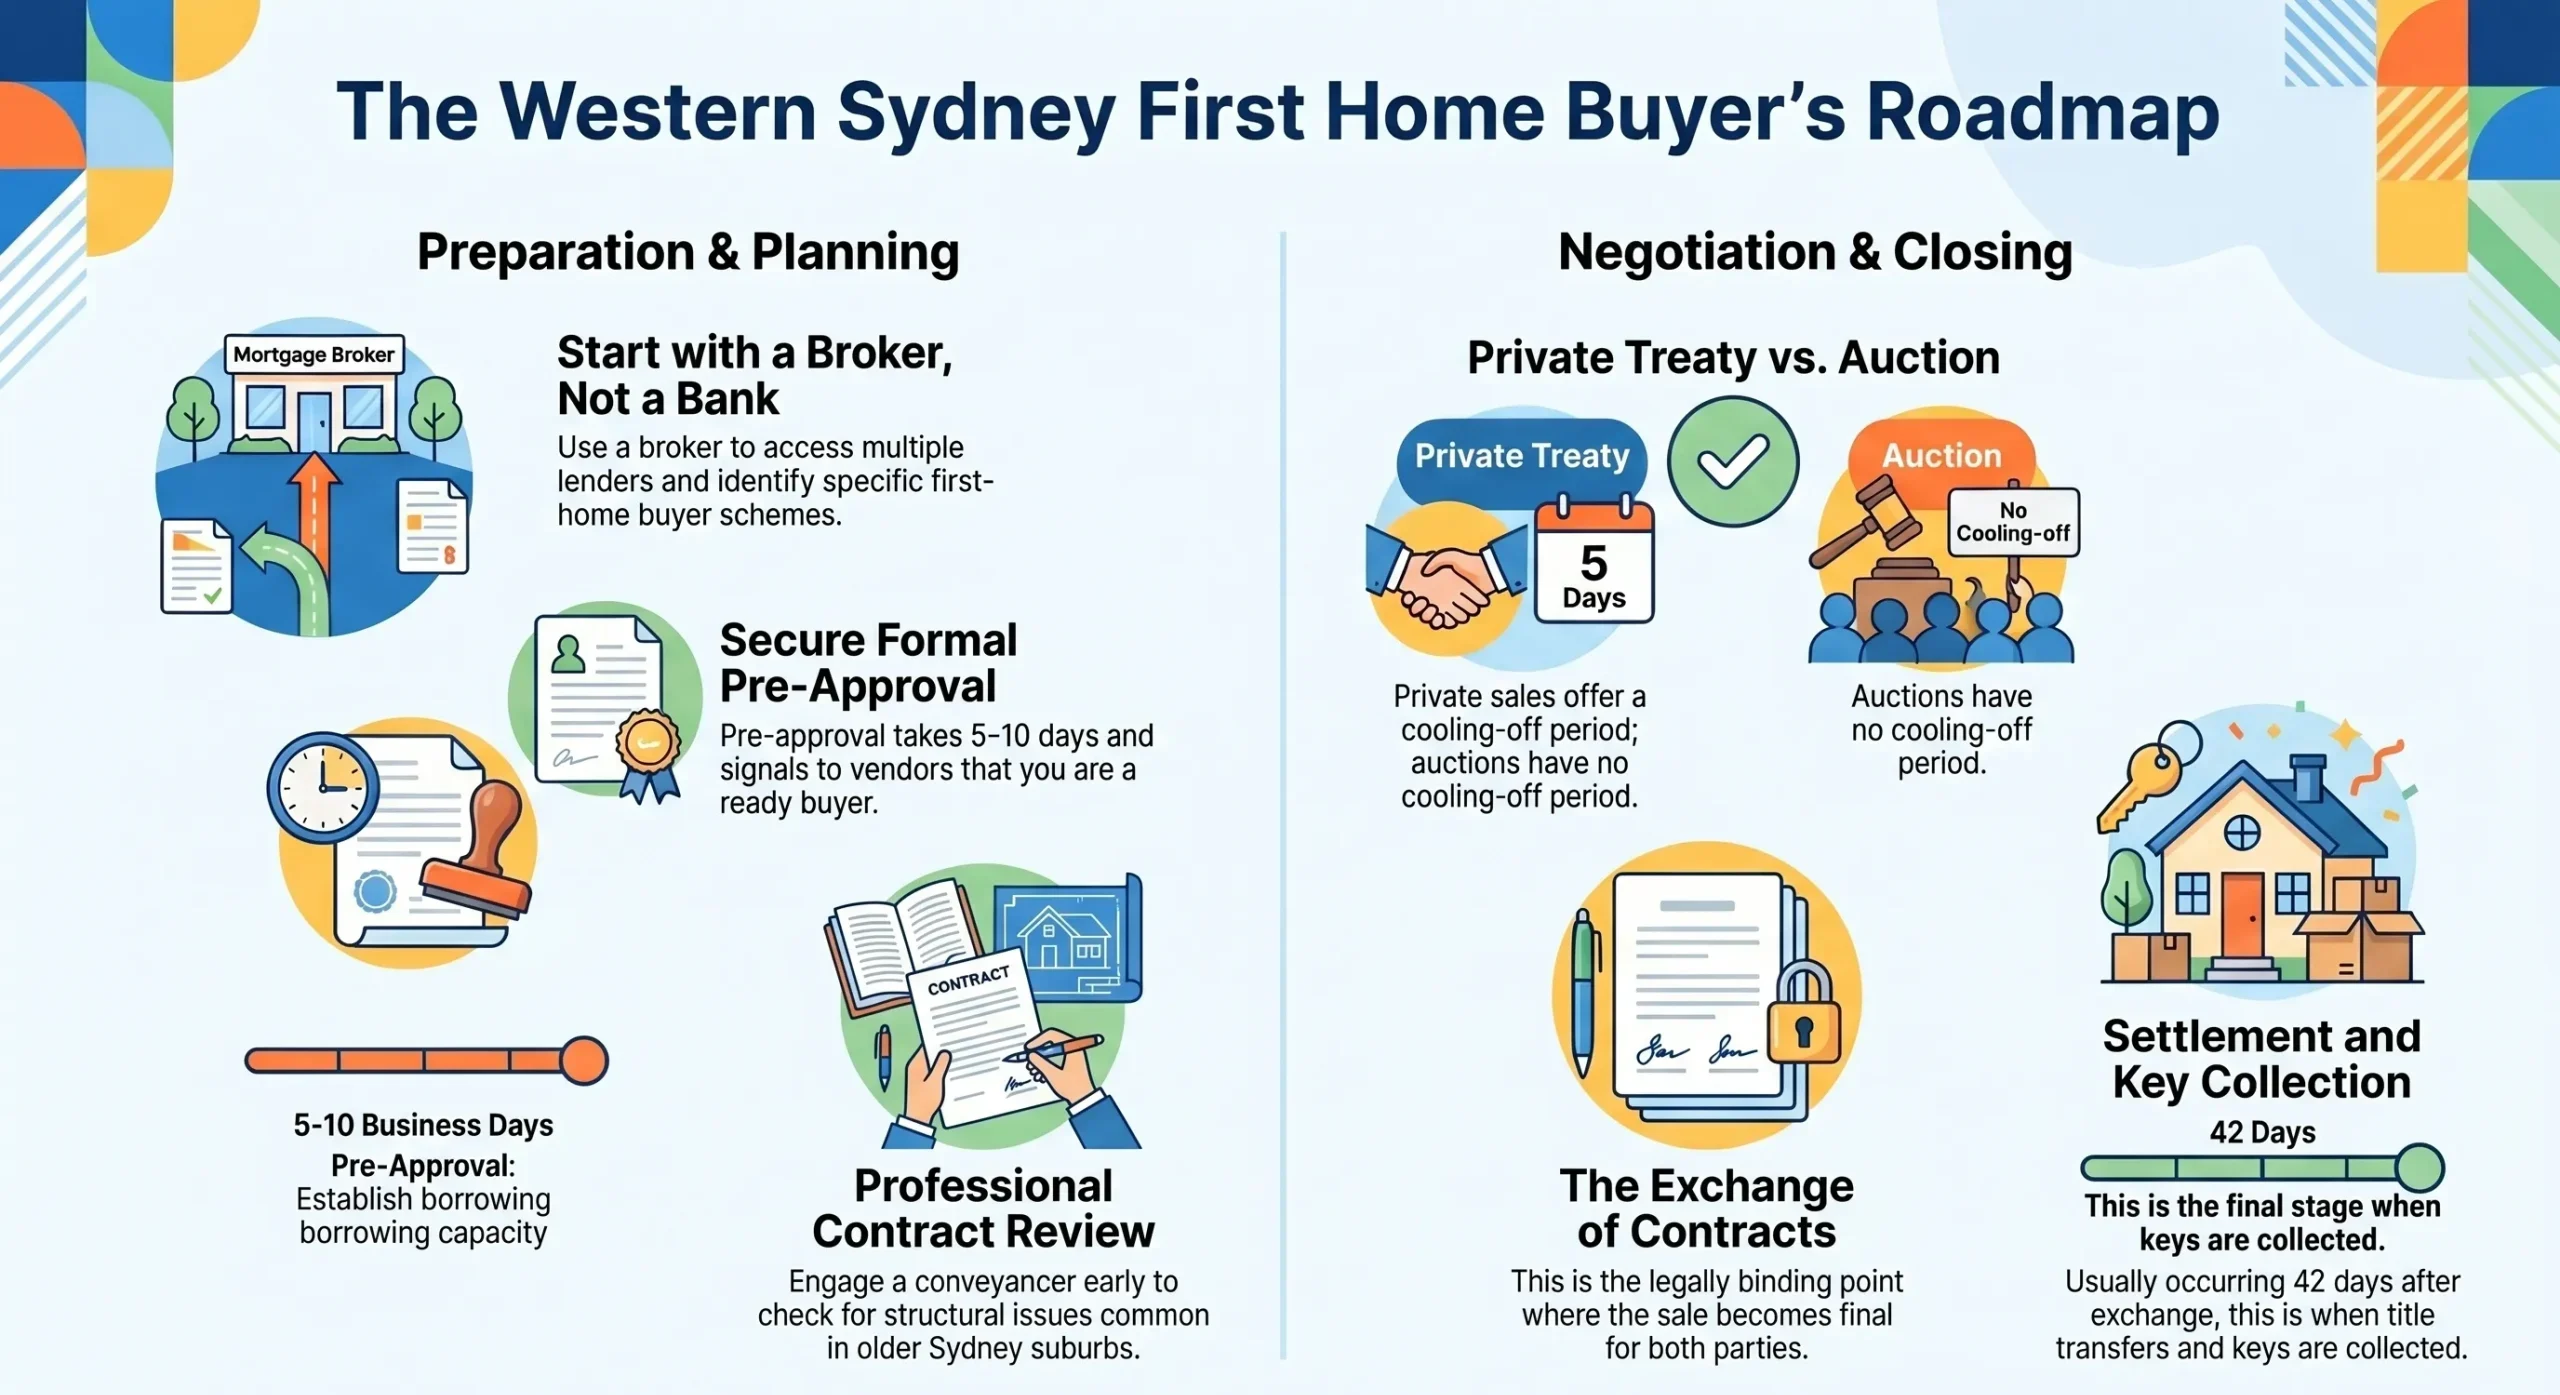
Start with a mortgage broker appointment — not a bank. A broker has access to multiple lenders and can identify which products and rate structures suit your situation. In Western Sydney, there are several mortgage brokers who specialise in first home buyer schemes and know the local market well.
Key questions to establish before searching:
- What is your borrowing capacity at current interest rates?
- What deposit do you have, and how does that affect your LMI exposure?
- Which first home buyer schemes do you qualify for?
- What is the total amount you can spend, including stamp duty (or your savings from the exemption), legal fees, building inspection, and moving costs?
Step 2 — Confirm Your Grant Eligibility
Before signing any contract, confirm your eligibility for the FHOG and FHBAS with Revenue NSW directly. Applications are lodged at settlement — but eligibility must be confirmed before exchange. Revenue NSW has a free online eligibility checker.
For the First Home Guarantee, apply through a participating lender as part of your mortgage pre-approval process. For Help to Buy, check Housing Australia’s current registration process as this scheme launched in 2024 and is still being rolled out.
Step 3 — Get Pre-Approval
A formal mortgage pre-approval gives you a clear budget and signals to vendors and agents that you are a genuine, ready buyer — important in Western Sydney’s competitive market where properties in the first home buyer price range receive multiple offers.
Pre-approval typically takes five to ten business days and is valid for three to six months.
Step 4 — Engage a Solicitor or Conveyancer
You need a licensed conveyancer or solicitor before you exchange contracts. Many Western Sydney conveyancers offer fixed-fee first home buyer packages that include contract review, FHOG lodgement, and settlement.
Request a Section 10.7 certificate and building and pest inspection on any property you are seriously considering — particularly established homes. In Western Sydney, older properties in Blacktown, Parramatta, and Penrith can carry structural and drainage issues that are not visible without professional inspection.
Step 5 — Make an Offer or Bid at Auction
Western Sydney properties in the first home buyer price range are sold by private treaty (negotiated offer) more commonly than by auction. For private treaty sales, you have a cooling-off period of five business days after exchange — during which you can withdraw from the contract (with a 0.25% penalty).
For properties selling at auction, there is no cooling-off period. Do not bid at auction without pre-approval and a completed building inspection.
Step 6 — Exchange Contracts
Exchange is the legally binding point. Once both parties have signed and contracts have been exchanged, the sale is binding (subject to any conditions). Your conveyancer will manage this process and ensure your FHOG application is prepared for lodgement at settlement.
Step 7 — Pre-Settlement Inspection
You are entitled to one pre-settlement inspection in the final week before settlement. Use this to confirm the property is in the same condition as when you exchanged — all inclusions are present, no new damage has occurred.
Step 8 — Settlement
Settlement is typically 42 days after exchange for established properties — sometimes longer for new builds. At settlement, the balance of the purchase price is paid, title transfers to your name, and you collect the keys.
Your FHOG application (if applicable) is lodged by your conveyancer at settlement. The stamp duty exemption is processed through Revenue NSW as part of the transfer.
The Costs First Home Buyers in Western Sydney Often Miss
The purchase price is only part of what you need to budget. The following additional costs catch many first home buyers off guard:
| Cost | Typical Amount |
|---|---|
| Building and pest inspection | $400 – $700 |
| Conveyancing / legal fees | $1,500 – $2,500 |
| Mortgage registration fee | ~$150 |
| Lenders Mortgage Insurance (if <20% deposit, no guarantee) | $10,000 – $25,000 |
| Stamp duty (if above $800,000 threshold) | Up to $40,000+ |
| Moving costs | $500 – $3,000 |
| Immediate repairs or modifications | Variable |
| Total additional costs (under $800K, with FHBAS) | $2,500 – $6,000 |
| Total additional costs (over $800K, no exemption) | $15,000 – $50,000+ |
This is why maximising your eligibility for the FHBAS — and staying under the $800,000 threshold — is so financially significant for Western Sydney first home buyers.
Renting vs Buying in Western Sydney: Making the Right Decision for 2026
This is one of the most common questions first home buyers in Western Sydney ask, and there is no universal answer. The right choice depends on your personal circumstances, financial position, and how long you intend to stay in Western Sydney.
The case for buying now:
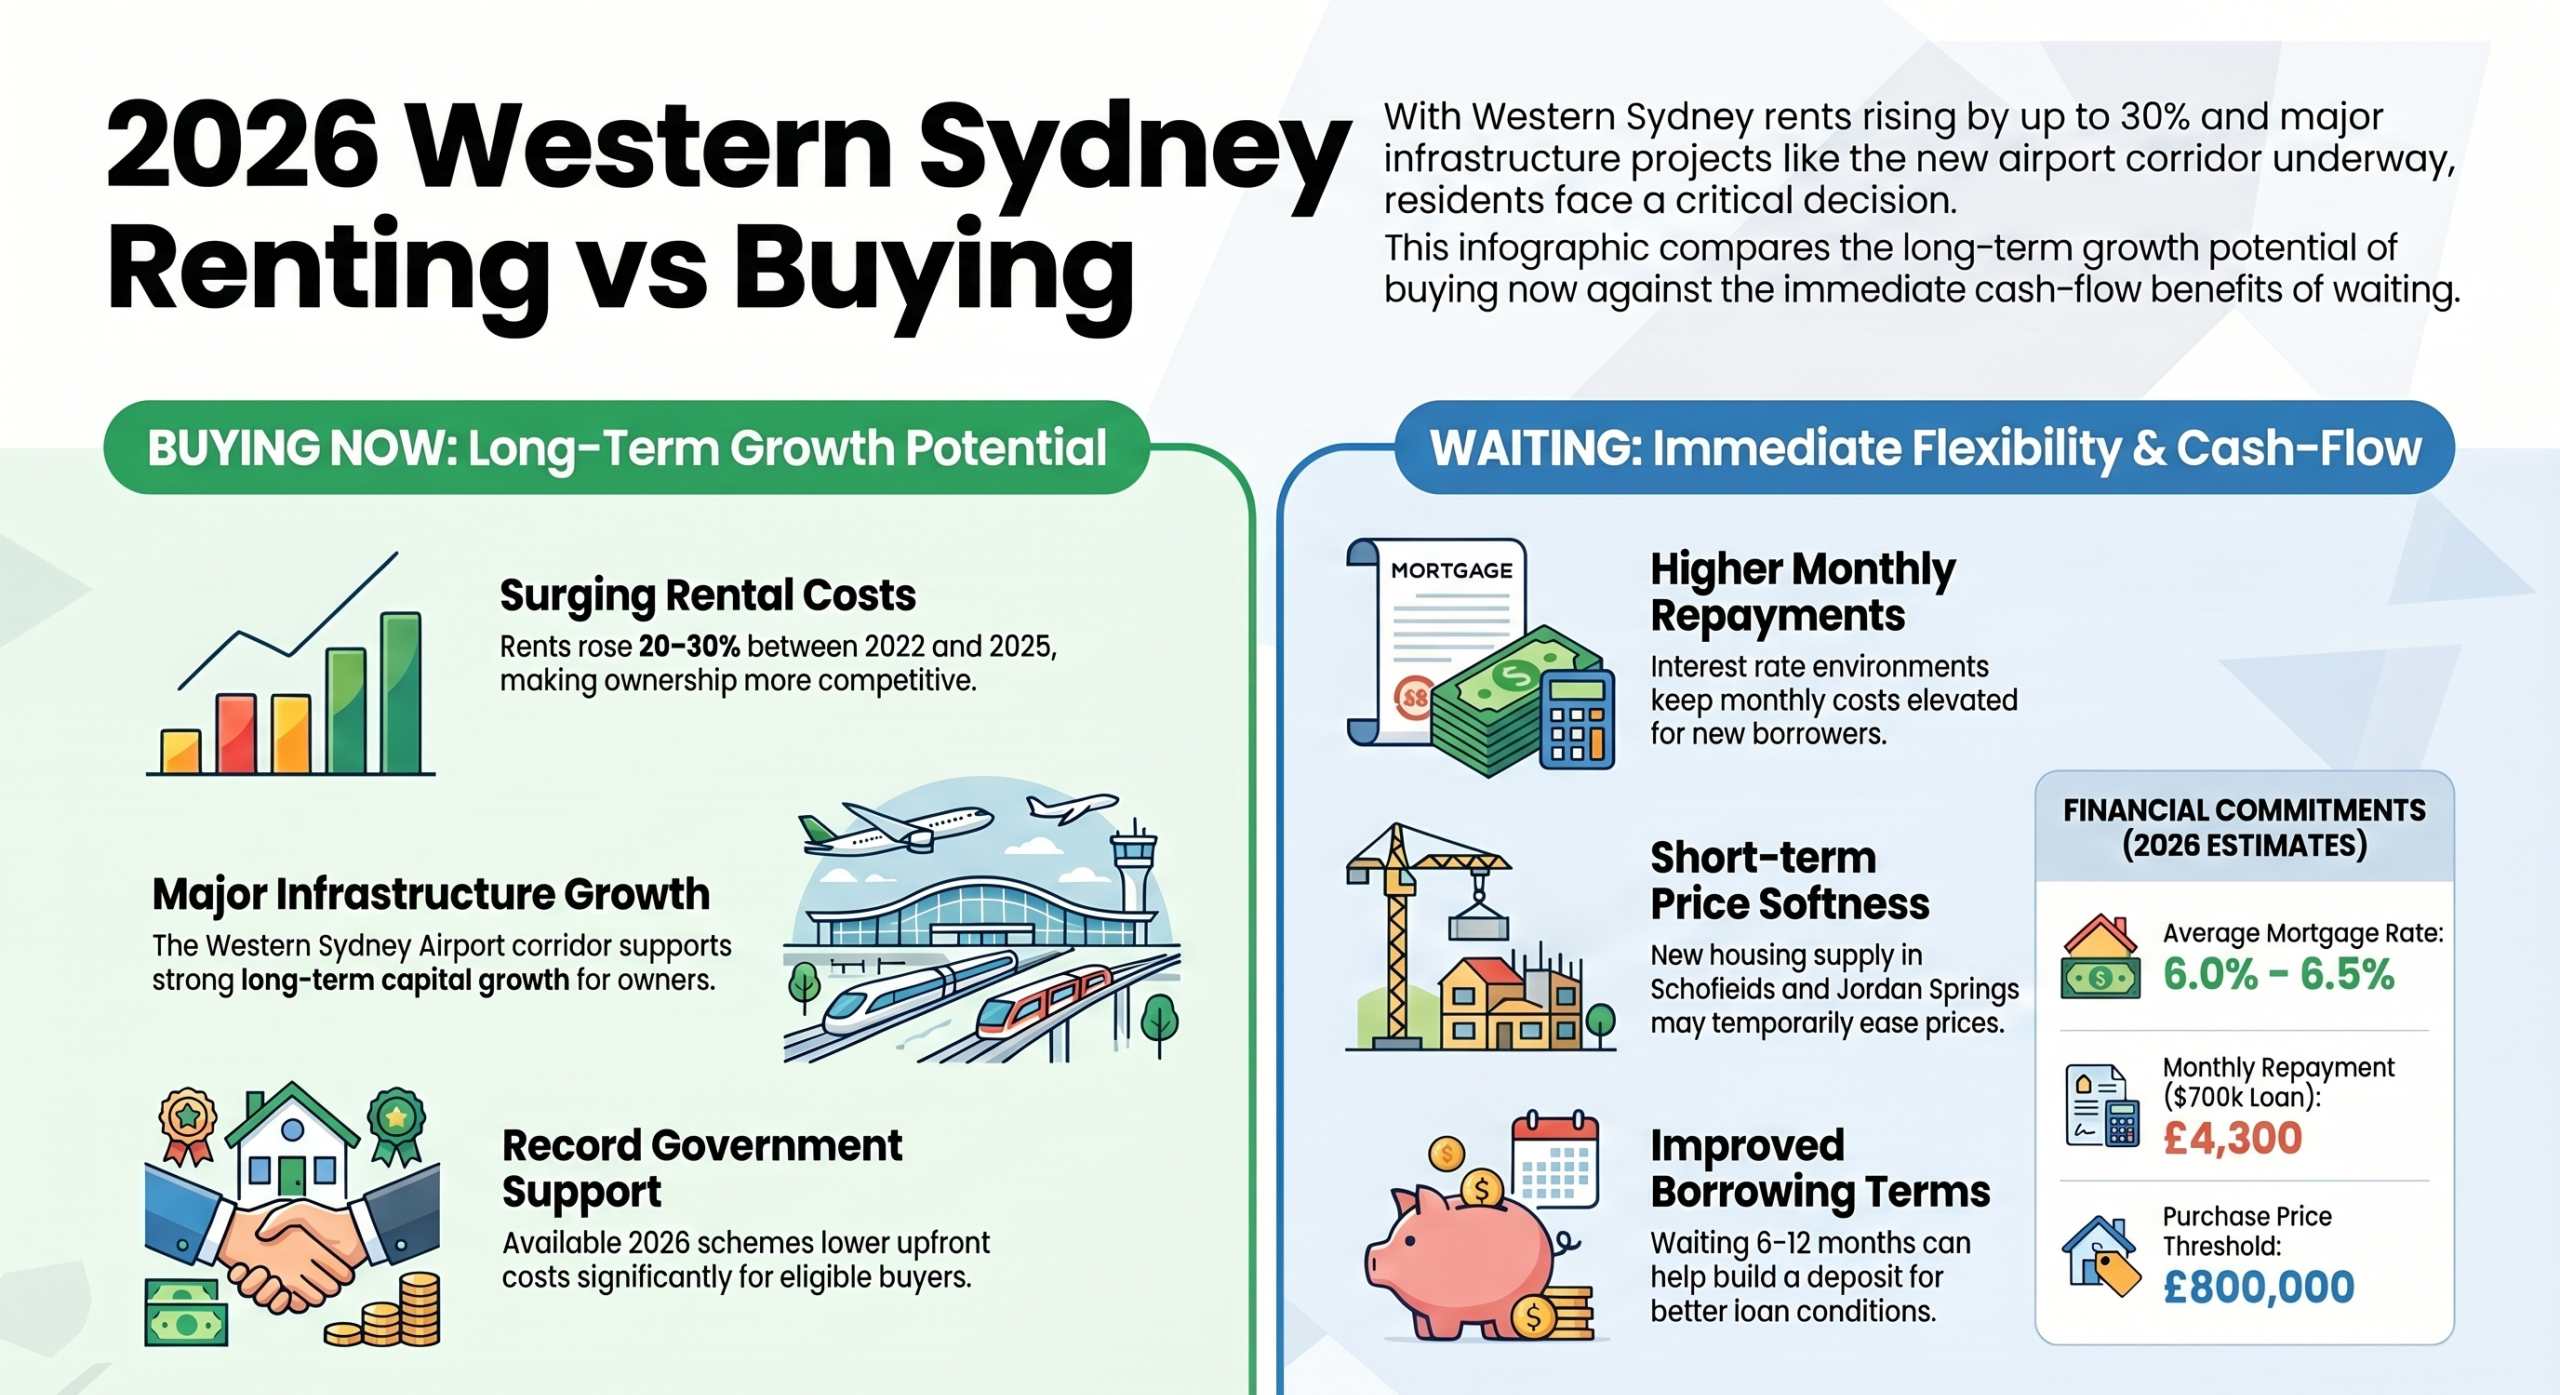
- Western Sydney rents increased 20–30% between 2022 and 2025, making renting increasingly expensive relative to ownership costs
- Government support packages make the upfront cost lower than at any point in recent years
- Western Sydney’s infrastructure investment — particularly the Western Sydney Airport corridor — supports long-term capital growth
- Locking in your mortgage rate now provides certainty against future rent increases
The case for waiting:
- At current interest rates (approximately 6.0% to 6.5% for owner-occupier loans), a $700,000 mortgage at 6.25% costs approximately $4,300 per month in repayments — more than renting a comparable property in most Western Sydney suburbs
- If you are still building your deposit, waiting six to twelve months to access a better deposit position can meaningfully improve your borrowing terms
- New supply in suburbs like Schofields and Jordan Springs means short-term price softness is possible
The honest answer: if you have a 5% deposit, confirmed scheme eligibility, a stable income, and you have found a property within the $800,000 threshold that meets your needs — buy. The government support available in 2026 meaningfully changes the financial equation compared to previous years.
Western Sydney First Home Buyer: Common Mistakes to Avoid
Not getting pre-approval first. In Western Sydney’s first home buyer price range, quality properties receive multiple offers quickly. Without pre-approval, you cannot move fast enough.
Exceeding the $800,000 threshold unnecessarily. Spending $810,000 instead of $800,000 costs you approximately $3,000 in concessional stamp duty. The $800,000 threshold is a hard line worth respecting.
Confusing the FHOG threshold with the FHBAS threshold. The FHOG applies to new homes under $600,000. The FHBAS full exemption applies to any property under $800,000. These are different schemes with different property type requirements — many first home buyers assume they are the same.
Skipping the building and pest inspection. For established properties, a building and pest inspection is essential — particularly in older Western Sydney suburbs where drainage, asbestos, and structural issues are common. A $500 inspection can save you from a $50,000 problem.
Not using a mortgage broker. A mortgage broker accesses 20+ lenders and can identify rates, features, and structures that are not available through a single bank’s branch. For first home buyers navigating scheme eligibility, a broker is essential.
Buying at the absolute limit of your borrowing capacity. At current interest rates, buying at the maximum of your borrowing capacity leaves no buffer for rate rises, job changes, or unexpected costs. A 10% to 15% buffer below your maximum borrowing capacity is prudent.
How Real Homes Realty Helps First Home Buyers in Western Sydney
Real Homes Realty has helped buyers across Western Sydney navigate the first home buying process for over 12 years. We know which properties in Penrith, Blacktown, Parramatta, Kellyville, and Jordan Springs are realistically available within first home buyer price thresholds — and we can advise on the suburb-level differences in value, growth prospects, and lifestyle that matter most when choosing your first home.
Our team can:
- Provide a current market assessment for any Western Sydney suburb
- Identify properties currently available within your budget and scheme eligibility
- Explain what to look for at inspections and what questions to ask
- Refer you to trusted local mortgage brokers and conveyancers who specialise in first home buyer transactions in Western Sydney
👉 Browse properties for sale in Western Sydney 👉 Contact our team today 👉 Request a free market appraisal
External Resources
- Revenue NSW — First Home Buyers Assistance Scheme
- Revenue NSW — First Home Owner Grant
- Housing Australia — First Home Guarantee
- Housing Australia — Help to Buy
- ATO — First Home Super Saver Scheme